
Three in four (75%) urban Indians have used at least one financial product—investments, insurance or credit—within their payment app, according to the How Urban India Pays report 2026, released by Pahlé India Foundation in collaboration with Amazon Pay. Yet this confidence has not extended equally to digital credit, where awareness is high (88%) but usage remains low (31%).
The report surveyed 5,149 consumers and 1,089 merchants across 100 cities in 20 states.
UPI leads in five of six spending categories: 71% use it for ecommerce, 54% for eating out and travel, 53% each for fuel and medical expenses, and 49% for groceries. Cash holds on mainly for rent, where it accounts for 49% of payments. More than half (52%) of consumers say they would prefer a single app for payments, investments, insurance and credit.
At the consumer level, the impact shortfall is rooted in trust. With UPI leading in five of six spending categories, consumers rate their payment apps 4.11 out of 5 for security and 3.98 for payments, but just 3.10 when the same app offers credit. The gap looks solvable: 51.5% say they would borrow through their app if fraud protection were guaranteed, versus just 16.7% who would still decline.
“What stands out this year is how confidently urban India is adopting digital credit to manage everyday finances. Consumers are increasingly turning to BNPL and EMI options not just for big-ticket purchases, but as practical tools to spread costs, stay within budget and make aspirational purchases more accessible. At Amazon Pay, we see this shift first-hand, with 75% of our customers in Tier-2 and Tier-3 cities. Our focus is on making credit simple, transparent and relevant so that every customer can plan better, spend smarter and fulfill their aspirations with confidence,” says Vikas Bansal, CEO, Amazon Pay India.
“India’s digital payments revolution is one of the more remarkable achievements of our development journey. In less than a decade, UPI has moved from novelty to reflex, and urban India now pays digitally as a matter of habit. Having built this foundation of trust-based efficiency at scale, India is now ready for its next leap: extending the confidence earned in payments to borrowing, saving and investing. With transparent disclosure, robust cybersecurity and safety, and underwriting that recognises informal incomes, digital finance can reach every Indian and make a meaningful contribution to the goal of Viksit Bharat @ 2047,” says Dr Rajiv Kumar, Chairman, Pahlé India Foundation.
Key findings from the How Urban India Pays Report 2026
- From payment app to financial companion: The appetite for consolidation is strong: 52% would prefer a single app for payments, investments, insurance and credit, while another 33% would consider it if the app matched dedicated platforms feature-for-feature.
- Digital payments are now everyday habit: UPI is the most-used payment method: 71% use it for e-commerce, followed by eating out and travel (54%), fuel and transport (53%), medical and pharmacy (53%), and groceries (49%).
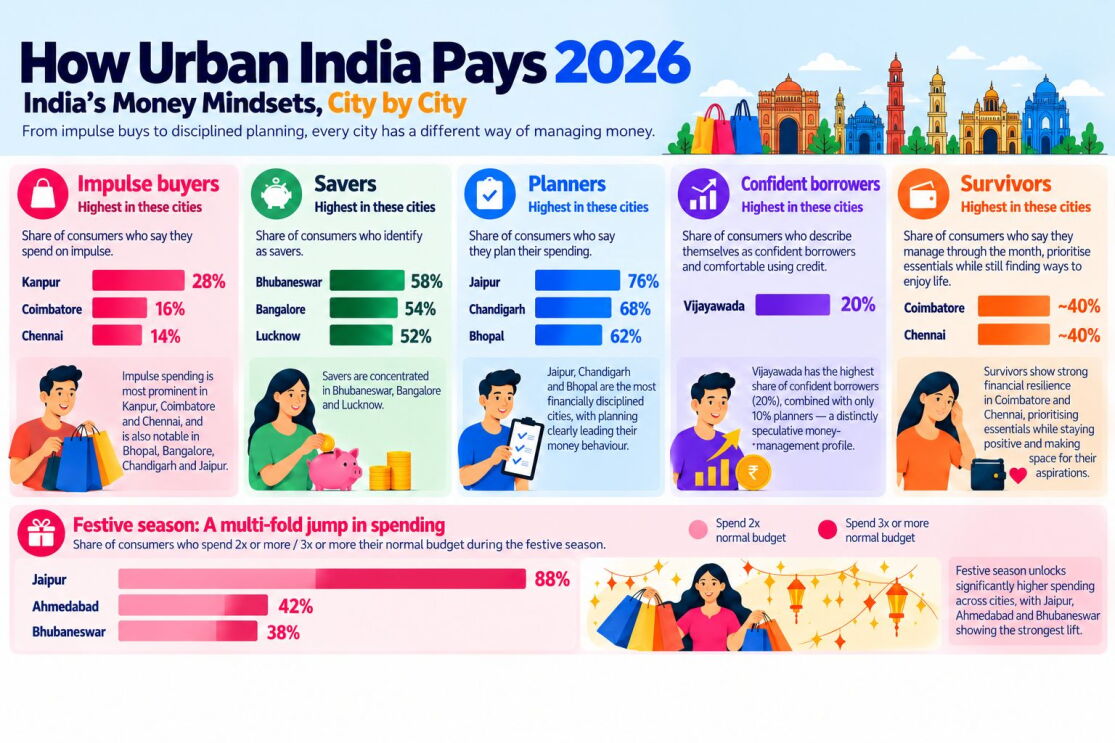
- Festive season drives a spending surge: 77% of respondents spend at least 50% more than usual during the festive season — 46% report spending 1.5–2× their regular budget, while 6% spend more than three times as much. At a city level, Rajkot and Ahmedabad record the highest shares of respondents spending three times or more, while Jaipur stands out with 88% spending at least double their usual budget. Consumer Electronics and Home Appliances account for the highest-value purchases, while Fashion & Beauty leads in purchase volume (89%), followed by Home & Kitchen (87%) and Everyday & Grocery (84%).
- Tier-2 cities lead the digital financing charge: Tier-2 cities emerge as the next growth engine for digital credit, with usage higher than in metros across every product measured. Tier-2 leads BNPL (60%) and credit applications (41%), with a Digital Credit Inclusion Index (DCII) score of 58.64 that exceeds both Tier-1 (53.10) and Tier-3 (55.77). City-level data reveals sharp differences: Coimbatore records the highest use of instalment financing for electronics and appliances at 70%—nearly 10X the national norm—followed by Kochi at 45%. Surat, Bengaluru and Chandigarh show the strongest BNPL adoption for fashion, while Mumbai’s festive shopping is dominated by credit cards.
- Gig workers show strong digital-credit appetite: Gig workers combine high digital-finance engagement with clear unmet credit need: 67.5% use UPI Lite regularly, 23% would turn first to a digital loan app in a cash crunch (3.4X the national norm), and 43% say digital credit has increased their financial independence. Yet informal earners — including gig workers, daily-wage workers, homemakers, students and the unemployed — score about 11 points below salaried and business respondents on the DCII, reflecting the challenge of assessing irregular incomes through conventional underwriting.
- Senior citizens are more digitally confident than expected: 55% of senior citizens say digital payments make them feel confident and independent, and nearly half (49%) say their digital-payment use has become a regular habit over the past year.
- Merchants want digital payments, but faster settlements: Among merchants surveyed, 80.6% are open to digital payments and 79.5% report efficiency or sales gains since adopting them. Tier-3 merchants are the most enthusiastic, with 66.4% describing themselves as ‘Extremely Open’, ahead of Metro/Tier-1 (64.3%) and Tier-2 (51.7%). Where hesitancy remains, the issue is cash flow: 72.1% of hesitant merchants cite settlement delays as their primary concern.
Five ‘Money Minds’ shape urban India
The study identifies five financial personas: Planners (41%), Savers (33%), Survivors (15%), Impulse Spenders (7%) and Confident Borrowers (4%). Nearly three in four consumers identify as Planners or Savers. Survivors—characterised by greater caution around credit and a stronger reliance on savings and family—represent about one in seven, highlighting the importance of designing financial products around different consumer behaviours.
Thus, the How Urban India Pays Report 2026 highlights the growing role of digital payments and payment apps in shaping India’s financial landscape, with Tier-2 cities emerging as key drivers of digital-credit adoption. As consumers increasingly look to payment apps for a wider range of financial services, the next phase of growth will depend on building the trust needed to translate access into meaningful financial participation. Strengthening fraud protection, improving transparency and developing credit solutions that account for diverse income patterns will be critical to ensuring that the benefits of digital finance extend to more Indians.